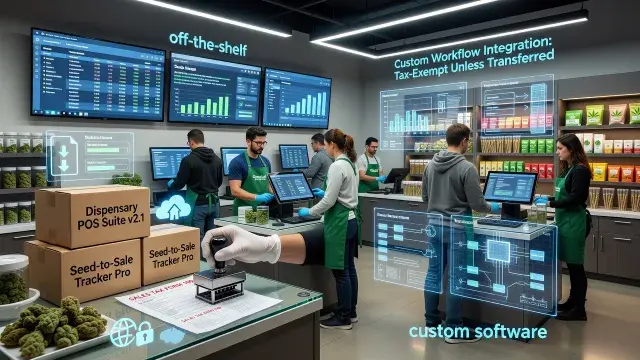
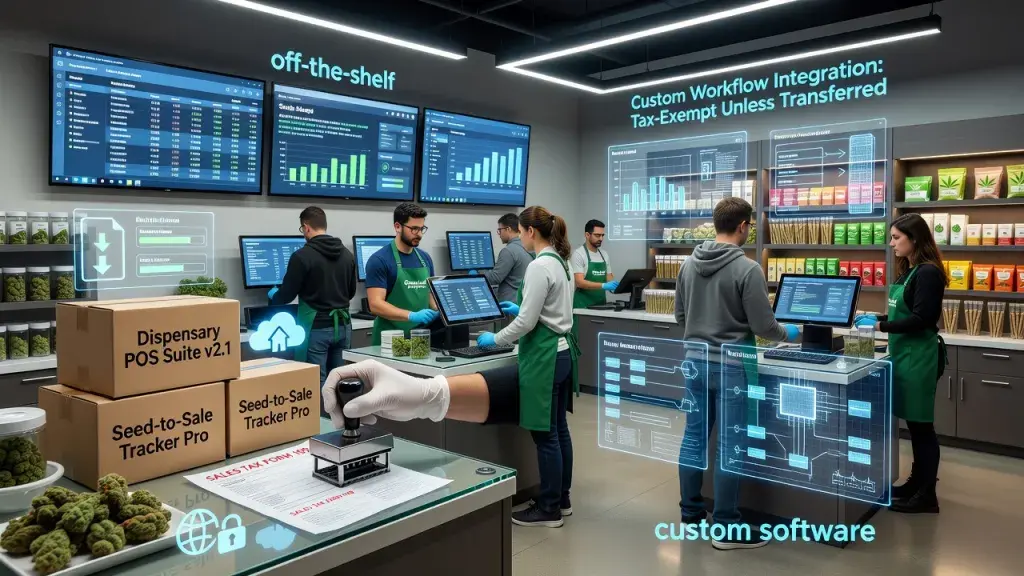
Cannabis retailers running on seed-to-sale platforms, point-of-sale terminals, or custom compliance dashboards need to understand something that has nothing to do with THC limits or packaging rules: how sales tax applies to the software powering their stores. The distinction between prewritten and custom software determines whether a dispensary's technology stack carries a tax bill on top of its licensing fees - and for multi-state operators juggling different POS vendors across jurisdictions, that distinction adds up fast.
Prewritten Versus Custom Software - Why the Line Matters
Prewritten computer software is taxable as tangible personal property. It doesn't matter whether a dispensary buys it on a disk, downloads it, or accesses it remotely through the cloud. If the software wasn't built to that specific operator's specifications, it's prewritten - full stop. That covers most off-the-shelf seed-to-sale platforms, inventory management tools, and standard POS software that dispensaries license from vendors serving the wider retail market.
Custom software is different. If a vendor designs a compliance system specifically for one operator's workflow - say, a bespoke integration between a delivery manifest system and a state's track-and-trace reporting - that build is exempt from tax, provided it stays with the purchaser it was built for. Sell or transfer that custom build to another operator, and it becomes taxable at that point. The thing is, a lot of "custom" dispensary software isn't really custom at all; it's a prewritten core with some modifications layered on top, and that distinction has real tax consequences.
Modifications, Upgrades, and the Separately Stated Invoice
Here's the catch that trips up a lot of software vendors serving cannabis retailers: modifying or enhancing prewritten software to fit a client's specifications is still taxable, unless the charge for that customization work is reasonable and separately stated on the invoice. Bundle it into one lump-sum fee, and the whole thing gets taxed. Break it out clearly, and the modification charge can be exempt while the underlying prewritten license remains taxable.
The same logic applies to upgrades. A routine software revision or upgrade is generally taxed the same way as the original prewritten software sale. But if that upgrade was designed specifically for one purchaser's specifications, it qualifies as custom software and is exempt for that buyer alone.
Services tied to software - training, installation, troubleshooting, systems analysis, programming, repair, maintenance - are generally exempt. But when a vendor bundles those services with a prewritten software sale, the service charge stays exempt only if it's reasonable and separately stated on the invoice. Dispensary operators negotiating vendor contracts should ask for that itemization up front; it isn't a formality, it's what keeps part of the bill out of the tax base.
Remote Access, Cloud Platforms, and Local Tax Situs
Most modern dispensary software runs on remote access - cloud-based POS, cloud-hosted compliance logs, SKU management dashboards accessed through a browser. Under this framework, remote access counts as a transfer of possession, because the purchaser gains constructive control over the software even without ever touching a server. That means a license to remotely access software is taxable the same way a physical software sale would be.
For multi-state operators, the tax situs question gets complicated. The location that determines the applicable local tax rate isn't where the code lives - it's where the purchaser's employees actually use or direct the use of the software. An operator with budtenders and back-office staff using the same platform across multiple store locations in different tax jurisdictions should expect the vendor to allocate and collect tax based on where each user is located, not where the company's headquarters sits.
Maintenance Agreements and Narrow Exemptions
Separately stated, reasonable charges for maintaining, servicing, or repairing software are exempt. But maintenance agreements that bundle taxable elements - like software upgrades - with nontaxable services get taxed in full unless the nontaxable pieces are itemized both in the agreement and on the invoice. Dispensary operators signing annual maintenance contracts with their compliance software provider should look closely at how those contracts break down charges; a poorly itemized agreement can turn an otherwise exempt maintenance fee into a fully taxable one.
There are narrower exemptions too. Prewritten software used directly and predominantly in producing tangible personal property for sale, or in research and development, can qualify for exemption with a properly completed exemption certificate. Custom software transferred within an affiliated group of corporations or a related partnership can also stay exempt, provided the transfer isn't structured mainly to dodge tax and the software isn't something the vendor sells generally in the ordinary course of business.
None of this changes how dispensaries handle age verification, lab testing, or compliant packaging - the operational core of cannabis retail stays the same. But as more of that operational core runs on licensed software rather than paper logs, understanding how tax law treats that software isn't a back-office footnote. It's part of running a compliant, financially sound retail operation.